 ultimate-guide
7 Real Ways to Understand What 1 Million Dollars Buys
Last Updated: October 25, 2026
Quick Summary
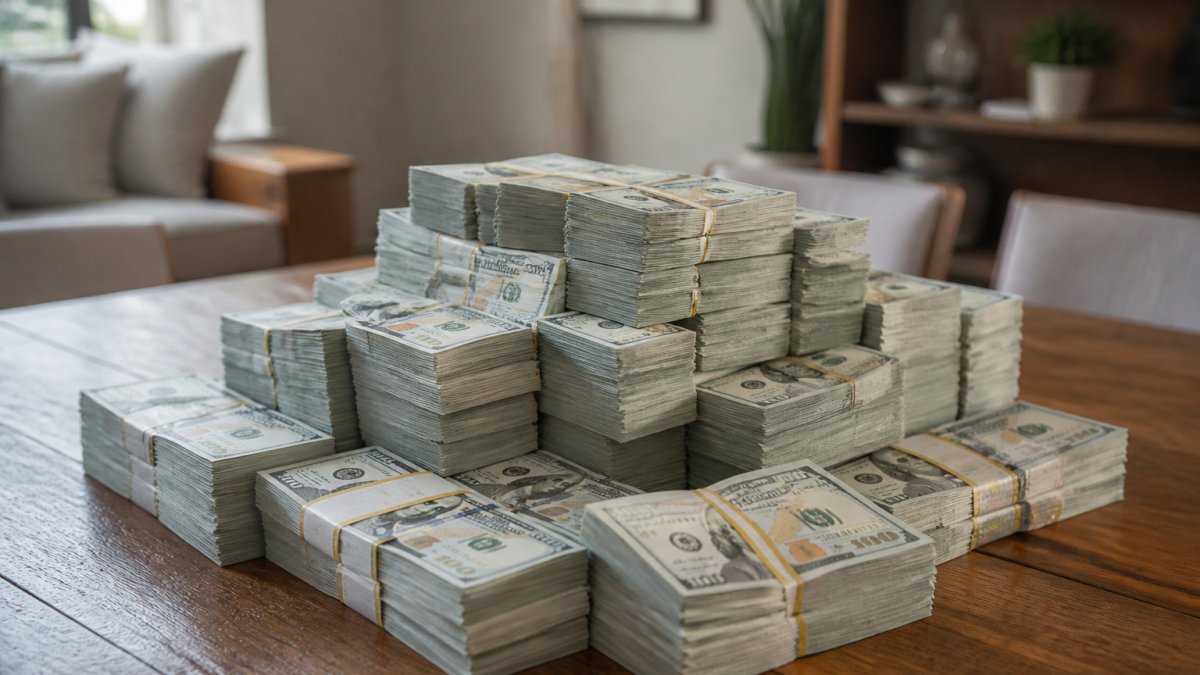
1 million dollars is a compact stack of banded $100 bills weighing about 10 kilograms, and as net worth it places you in the top 1% globally and around the 88th percentile of American households. What it buys depends on where you live and how you withdraw it.
- One million dollars in $100 bills weighs roughly 10 kilograms and fits in a standard briefcase.
- A 4% withdrawal on $1 million is $40,000 in year one; a 3% draw is $30,000.
- At 3% annual inflation, $1 million in 2026 has the purchasing power of about $553,000 in 2046.
- Keep twelve to twenty-four months of essential expenses in cash or short-term Treasuries as a buffer.
- A 1% advisory fee on $1 million is $10,000 a year before fund expenses.
Table of Contents
- What Does $1 Million Look Like in Cash and Net Worth?
- How Much Is $1 Million in Physical Cash?
- What Can You Do With One Million Dollars?
- How Long Does $1 Million Last?
- What to Do When Your Net Worth Reaches $1 Million
- How $1 Million Compares With Typical Household Wealth
- Start Building Your First $1 Million With a $6 Digital Reseller Site
- Frequently Asked Questions
What Does $1 Million Look Like in Cash and Net Worth?
One million dollars is a number most people never picture clearly. In cash, it is a compact stack of banded notes. In net worth, it is a milestone that puts you in rare company. This guide from $6 Dollar Millions breaks down what 1 million dollars represents, what it buys, how long it lasts, and what to do once you cross that line.
The distinction matters more than most people realize. According to A Wealth of Common Sense's 2026 analysis, the global millionaire population rose 7.9% to 25.3 million in 2025, and $1 million in liquid net worth would place someone in the top 1% globally and the 88th percentile of American households. That single sentence captures the tension: a million dollars is elite on a world scale and merely comfortable in parts of the United States.
Net worth is your assets minus your liabilities. Cash, home value, brokerage accounts, and retirement funds count; debt subtracts. A person with a $1.2 million house and a $900,000 mortgage is not a millionaire in any meaningful sense.
How Much Is $1 Million in Physical Cash?
One million dollars in $100 bills weighs roughly 10 kilograms and fits in a standard briefcase. In $20 bills, it weighs about 50 kilograms and needs a suitcase.
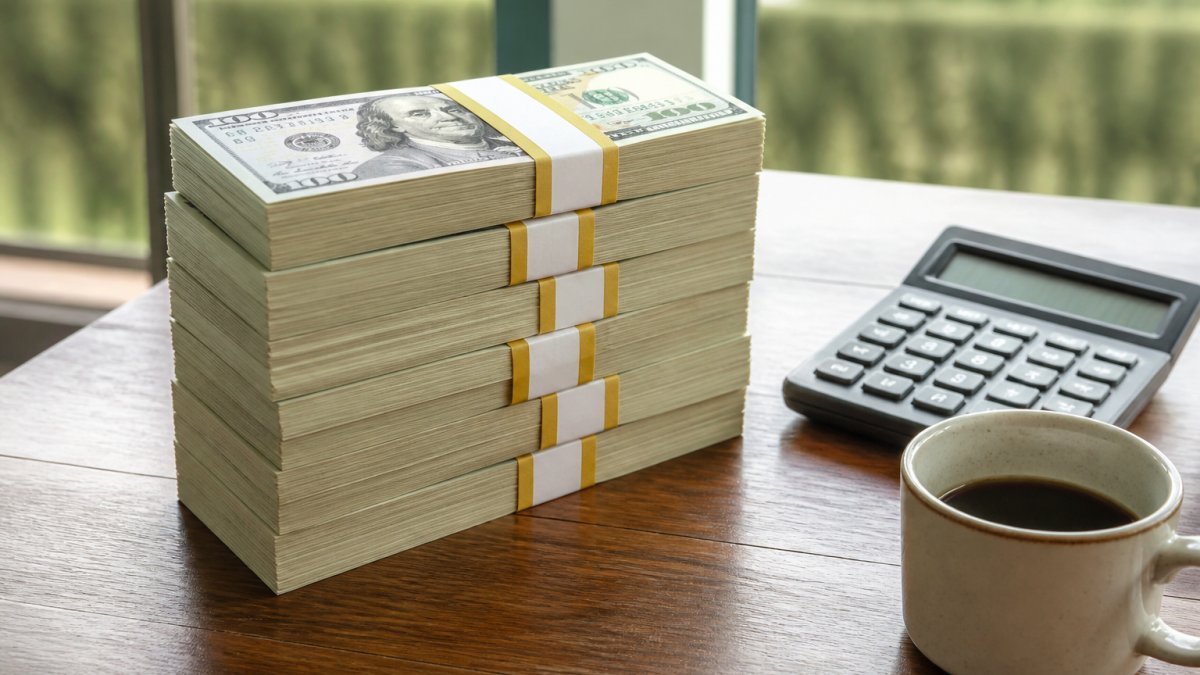
Here is the breakdown by denomination:
| Denomination | Number of Notes | Approximate Weight |
|---|---|---|
| $100 bills | 10,000 | 10 kg |
| $50 bills | 20,000 | 20 kg |
| $20 bills | 50,000 | 50 kg |
| $10 bills | 100,000 | 100 kg |
The million-dollar bill does not exist as circulating currency; Federal Reserve notes top out at $100 (The Fed). Anyone offering a genuine million-dollar bill is selling a novelty, not money.
Watch out: holding $1 million in physical cash is a liability, not an asset. It earns nothing, it can be stolen, and large cash deposits trigger reporting requirements at most banks.
What Can You Do With One Million Dollars?
What you can do with one million dollars depends on where you live. In much of the world, $1 million buys a comfortable retirement. In Manhattan or San Francisco, it buys a modest apartment and little else.
The realistic options fall into a few buckets:
- Buy property outright in most mid-sized American metros, or put a substantial down payment on a home in an expensive coastal city
- Fund a retirement using a sustainable withdrawal rate, typically modeled at 3% to 4% per year
- Invest in a diversified portfolio of index funds, bonds, and cash reserves
- Start or buy a business, which carries the highest risk and the highest ceiling
- Travel, donate, or spend in ways that change your life rather than your balance sheet
A $1 million net worth removes financial fear, but it does not let you stop thinking about money. The difference between those two outcomes is planning.
If you want proven paths to build income toward that number, our guide on legitimate ways to earn online in 2026 lays out seven approaches that actually work.
How Long Does $1 Million Last?
$1 million lasts as long as your withdrawal rate, real return after fees and taxes, and spending pattern allow, variables a single "25 to 33 years" headline hides. Most practitioners model a 60/40 portfolio, assume a 3% to 4% initial withdrawal rate, and stress-test against bad sequencing, inflation, and fees.
Start with the withdrawal rate, not the balance. A 4% draw on $1 million is $40,000 in year one; a 3% draw is $30,000. Over 30 years, the 3% plan withdraws roughly $300,000 less in nominal dollars, the cushion against a long early downturn.
Then subtract fees and taxes. A portfolio charging 1% instead of 0.10% gives up roughly 0.9% of return every year, about $9,000 annually on $1 million before compounding. Taxes depend on account type: tax-deferred withdrawals are taxed as ordinary income, qualified Roth withdrawals are not, and taxable accounts face capital gains rules.
Model scenarios rather than a single answer. A simple way to see the range is to compare three plans on the same $1 million:
- Conservative: 3% initial withdrawal ($30,000/year), 60/40 portfolio, 0.25% all-in fees, 3% inflation. This is the plan most likely to survive 30+ years and leave a residual balance.
- Moderate: 4% initial withdrawal ($40,000/year), similar portfolio and fees. Historically this has worked over 30-year horizons in U.S. data, but it has failed in some international and high-inflation periods, and it is more sensitive to a poor first decade.
- Aggressive: 5%+ initial withdrawal ($50,000+/year). This shortens the expected lifespan of the portfolio substantially and depends on strong returns or a shorter time horizon.
Sequence-of-returns risk is the variable most people miss. Two retirees can earn the same average return over 30 years yet end very differently if one hits a sharp decline in the first five years while withdrawing. Common mitigations: hold 12 to 24 months of spending in cash or short-term Treasuries, and use a "guardrail" approach, cut spending after bad years, raise it after good ones.
Inflation is the quiet killer. At 3% annual inflation, $1 million in 2026 has the purchasing power of roughly $744,000 in 2036 and about $553,000 in 2046. A 4% withdrawal that feels comfortable at 60 can feel tight at 80, which is why many planners model spending in real, inflation-adjusted terms.
The practical takeaway: $1 million supports roughly $30,000 to $40,000 of pre-tax spending per year under common assumptions, with the lower end more durable and the higher end requiring a shorter horizon, higher risk tolerance, or flexibility to cut spending. For readers who want to supplement that spending, see these passive income sites that actually work.
What to Do When Your Net Worth Reaches $1 Million
Crossing $1 million in net worth is a milestone, not a finish line, and the first year after you cross it is when most durable decisions get made.
1. Separate liquid from illiquid. Count only what you could access within 30 days without penalty or a forced sale. Home equity, private business stakes, and locked retirement accounts count toward net worth but not flexibility.
2. Build the cash reserve first. Twelve to twenty-four months of essential expenses in cash or short-term Treasuries is the standard buffer.
3. Retire high-interest debt and review low-interest debt deliberately. Eliminate credit card and other high-rate debt before any new investing.
4. Stress-test the withdrawal plan against your actual budget. Model a 3% draw against real expenses, housing, healthcare, taxes, travel, irregular costs, not a generic rule-of-thumb budget.
5. Rebalance and diversify the portfolio. A million-dollar portfolio that drifted to 80% equities during a bull run is riskier than its stated allocation suggests.
6. Review insurance and estate basics. At $1 million, gaps in health, disability, liability, and umbrella coverage can erase years of saving in a single event. Confirm beneficiaries and consider whether a simple will or trust is appropriate.
7. Review tax exposure across account types. Tax-deferred, Roth, and taxable accounts behave differently in retirement and in down markets.
8. Get professional advice proportionate to the complexity. A simple portfolio and tax situation may only need a one-time review; a business owner or someone nearing retirement likely benefits from ongoing advice.
How $1 Million Compares With Typical Household Wealth
A $1 million net worth places a household well above the American median, but the gap is smaller than most assume once mortgage and consumer debt are subtracted.
The comparison depends on the yardstick:
- Globally: $1 million in liquid net worth puts you in the top 1% of the world's population
- In the U.S.: the same figure puts you around the 88th percentile of households
- By age: a $1 million net worth at 35 is exceptional; at 65 it is closer to typical for the upper-middle class
The percentile conversation misses geography: $1 million in rural Mississippi has far more purchasing power than an identical household in San Francisco. Cost of living rewrites the meaning of the number.
Nacha's Same Day ACH rules now allow payments up to $1 million per transaction, which tells you something about how large transfers are treated in modern finance. A million dollars moves through the banking system as a routine transaction, not an event.
Start Building Your First $1 Million With a $6 Digital Reseller Site
The gap between wanting 1 million dollars and having it comes down to starting. Most people wait for a raise, an inheritance, or a "big idea" that never arrives. The faster path is a small, automated income stream that runs while you sleep.
That is exactly what $6 Dollar Millions delivers. For a one-time $6, you get a fully automated mini-site that sells digital packages and sends 100% of the profits straight to your PayPal account. No inventory, no technical skills, no monthly fees. The site handles sales and delivery 24 hours a day, and you own it for life.
We built it for beginners on purpose. The setup is simple, the marketing materials are included, and it is not a multi-level, pyramid, or matrix program. Skeptical readers should start with our honest take on whether an automated online business is a scam. It isn't, and we explain exactly why.
If you want the full playbook, our guide on how to generate income with reseller sites walks through the setup step by step. Ready to launch today? Our guide on starting an online store without inventory shows you how to go live in a single afternoon.
Frequently Asked Questions
How much is 1 million dollars in smaller denominations?
In $100 bills, $1 million weighs about 10 kilograms and fits in a standard briefcase. In $20 bills it weighs roughly 50 kilograms and fills a large suitcase. In $1 bills it weighs about 1,000 kilograms, which is why most people never see $1 million in physical cash. The form matters: cash, bank deposits, and investment assets all count toward a million-dollar net worth but behave very differently.
What can I do with 1 million dollars if I want it to last?
A common rule is the 4% withdrawal rate, which would let you take about $40,000 a year from a $1 million portfolio. That number changes with inflation, taxes, and investment returns. Many people split the money between a diversified portfolio, an emergency fund, and debt payoff before spending on lifestyle purchases. The goal is to keep the principal working so the money supports you for decades, not months.
How long does $1 million last if I stop working?
It depends on spending, inflation, and returns. At $40,000 a year, $1 million lasts 25 years with no growth. At $100,000 a year, it lasts 10 years. A diversified portfolio earning around 6% to 7% before inflation can stretch the timeline, but market risk and taxes reduce the real number. Most planners test several scenarios rather than relying on one figure.
What should I do when my net worth reaches $1 million?
First, separate gross wealth from spendable money. A $1 million net worth may include home equity and retirement accounts that you cannot access immediately. Next, review taxes, rebalance your portfolio, and set a sustainable withdrawal plan. Many people also increase their emergency fund and pay down high-interest debt. The milestone is a checkpoint, not a finish line, so keep investing and revisit the plan each year.
A million dollars is not a fantasy and it is not a finish line. It is a target you reach by stacking small, automated income streams until the math tips in your favor. $6 Dollar Millions gives you the first stream for less than the cost of lunch: a lifetime-owned reseller site, automated sales and delivery around the clock, and 100% of profits paid directly to your PayPal. Get started with $6 Dollar Millions and put your first dollar of automated income to work today.